30-Year Treasury Hits Highest Since 2007 As Global Bond Selloff Deepens
European yields jump; oil holds above $90 after Hormuz talks lapse
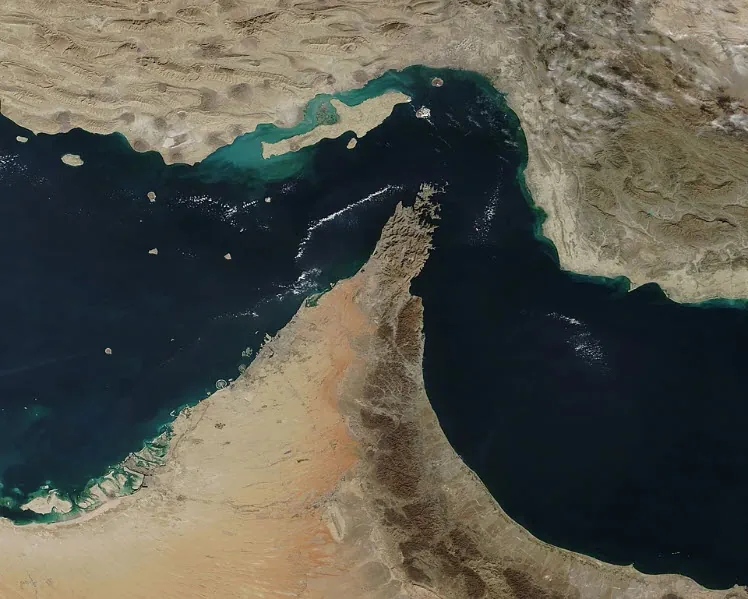
A global fixed‑income selloff intensified on August 18, 2026, sending long‑term government borrowing costs to new cycle highs and pressuring equities. In the United States, the 30‑year Treasury yield rose to its highest level since 2007, reflecting investors’ demand for greater term premium amid persistent inflation risks and elevated issuance. Crude benchmarks hovered above $90 after the 60‑day U.S.–Iran memorandum expired on August 17, 2026, rekindling concerns about shipping security through the Strait of Hormuz.
European government bonds registered fresh milestones as the rout widened: - Germany 10‑year: 3.2478% (highest since May 2011) - France 10‑year: 4.0954%; Bund–OAT spread 86 bps (widest since October 2025) - Germany 30‑year: 3.7663% (highest since July 2011)
The move matters because higher long‑duration yields filter quickly into the real economy. Governments face steeper refinancing costs just as fiscal needs remain elevated, while corporations confront pricier debt issuance that can delay capex and M&A. For households, sustained pressure at the long end typically pushes up mortgage rates and other fixed‑rate loans, weighing on housing and rate‑sensitive consumption. Equity valuations also compress as discount rates rise, a dynamic that has contributed to recent stock‑market weakness in multiple regions.
Energy markets are a key swing factor. Brent’s hold above $90—with traders citing renewed passage risks following the memorandum’s lapse—has reinforced concerns that fuel and transport costs could keep inflation stickier than central banks prefer. In Asia, analysts noted Japan’s long‑term rates have climbed toward the 3% area in recent sessions, approaching levels last seen in the mid‑1990s, underscoring how the global repricing is not confined to the U.S. and Europe.
Bottom line: cross‑currents from geopolitics, supply‑heavy bond calendars, and still‑firm inflation are pushing investors to demand materially higher compensation for holding duration. If these forces persist, elevated long‑term yields may prove less a spike and more a new baseline heading into the fall.